NDC adoption is no longer about replacing the GDS; it is about how individual airlines introduce new content and servicing capabilities through the distribution infrastructure agencies already use.
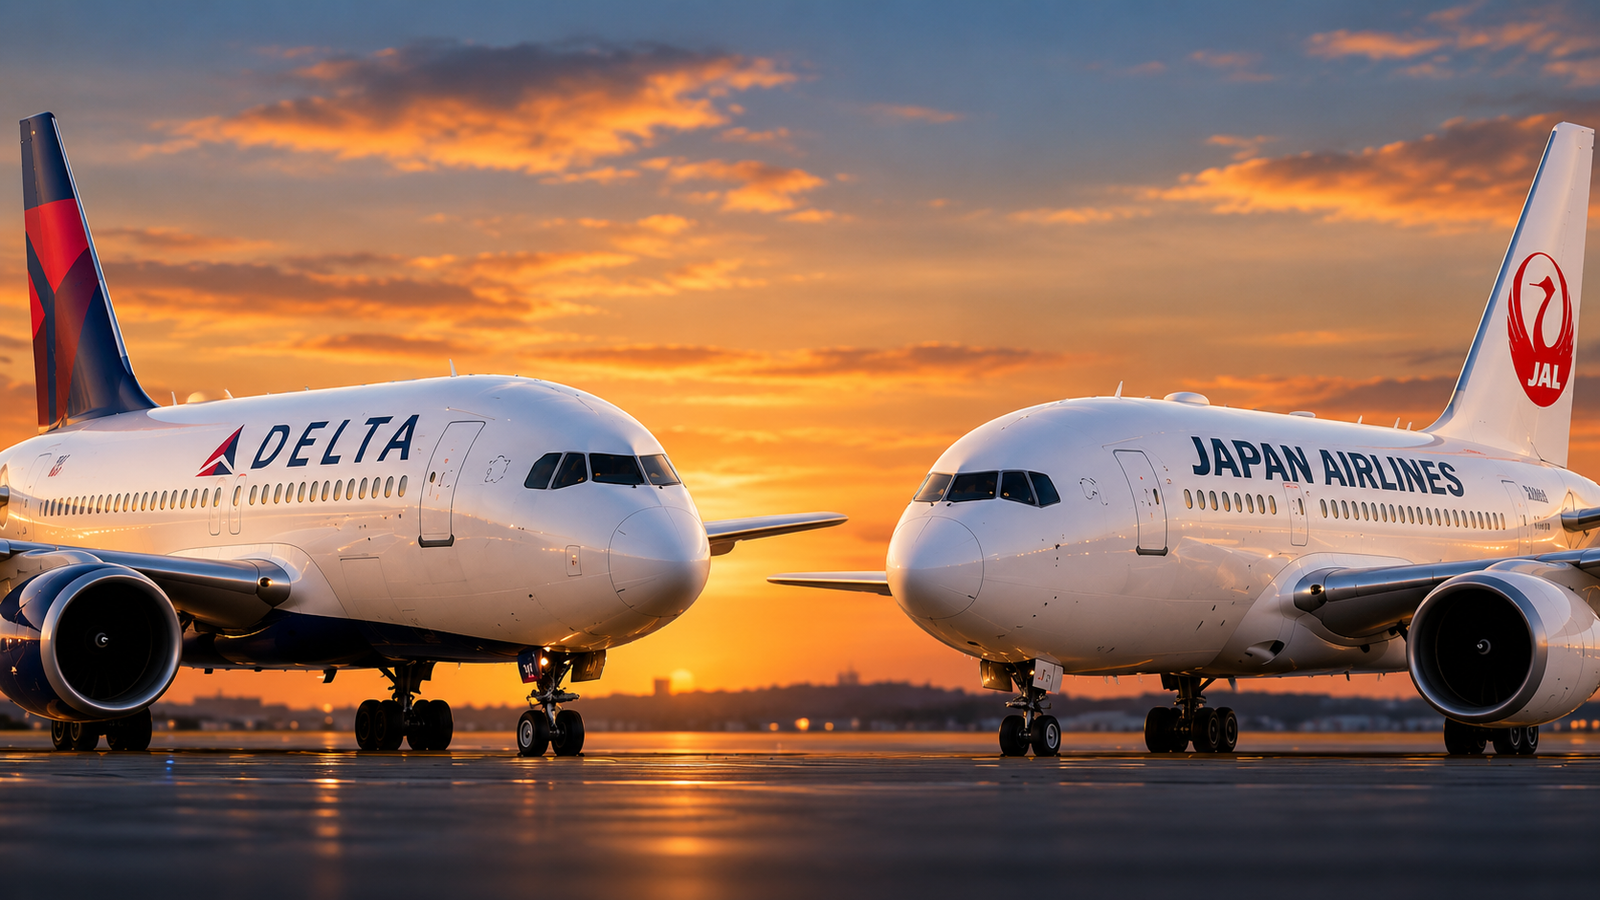
On September 24, two airlines on opposite sides of the world made NDC announcements on the same day. Read quickly, they look like more of the same. Read together, they describe two different ideas of what an NDC rollout is for.
Delta used its Business Showcase on September 24 to detail its NDC plans, reiterating that it expects to make NDC content available by the end of 2026, a timeline it first gave in late August. The airline has distribution agreements with Amadeus, Sabre and Travelport, plus select direct connections, and American Express Global Business Travel will carry Delta’s NDC offers in its marketplace. Delta says agencies will be able to search, book with immediate or delayed ticketing, and cancel orders with or without tickets issued. The most telling detail was Delta’s message to agencies not ready to move: they can keep working through Delta’s existing channels and workflows, and decide when NDC fits their future. Delta first said it would begin NDC testing in April 2024, so this is a rollout more than two years in the making, and it is being offered as an option, not a deadline.
JAL’s announcement was a different kind of commitment. From October 2026, JAL Group NDC content will be sold through the Amadeus Travel Platform. Sales began on October 1 in Japan and start on October 13 for overseas markets, with agencies in 26 countries and regions able to handle JAL Group NDC tickets progressively. JAL describes this as a first for a Japanese airline. It has also launched a dedicated website on NDC ticket sales. JAL is not new to the technology, having used Amadeus NDC technology since 2020. What changed is scale: a relationship that began as a technical integration is now a global distribution channel.
Put side by side, the two announcements show where NDC adoption has actually settled. Neither airline is asking the market to choose between NDC and the GDS. Delta’s NDC will reach agencies through the GDSs it already contracts with. JAL’s is going out through Amadeus, one of those same GDSs. In both cases the GDS is the pipe NDC travels through, which is why “NDC versus GDS” describes a fight the airlines themselves are not having.
The difference is in what each airline asks of the agent. Delta is explicit that legacy channels remain available, which lowers the cost of waiting. JAL’s rollout dates, by contrast, put a clock on agencies in 26 markets that want its full content. One airline is widening the choice, the other is widening the footprint. Both took years to reach this point, and both are now setting their own dates rather than waiting for the industry to move.
For emerging markets, the lesson is practical. Agencies in Africa and the Middle East are unlikely to meet NDC as a new relationship with a new vendor. They will meet it as a new content path inside the system they already use, arriving carrier by carrier, on each airline’s own timetable. The readiness question is not whether an agency can connect to NDC in the abstract. It is whether its GDS connection, its payment flows and its servicing processes can handle the offer and order logic when a carrier it depends on flips the switch.
That is the real shift behind September 24. NDC has stopped being primarily a technology announcement and become an operational calendar. The agencies that do well will not be the ones with the strongest opinion on NDC, but the ones that can read each airline’s calendar and be ready on the day it applies to them.