Airlines say Offers and Orders will keep them in charge of the customer as AI agents begin to shop for travel. The evidence from the past ten months points to something narrower: agents are reaching airline inventory first, largely at the airline’s expense, while the machinery that would let them buy, change and refund remains thin.
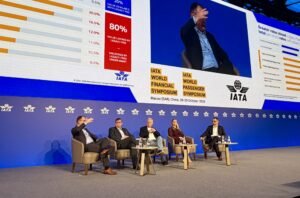
When Sandrine Le Borgne, IATA’s interim director general and chief financial officer, opened the World Financial and Passenger Symposium in Macao on 28 October, she reduced the commercial question to two sentences. AI assistants and automated agents are changing how travellers discover and compare options, she said, and the opportunity for airlines lies in preparing for that shift while retaining control of their data and their commercial relationships. Her shorthand for the strategy was that “Offers and Orders are the foundation; AI is the accelerator.”
The numbers IATA attached to that foundation were modest. Seven airlines are live with or implementing Orders, more than 20 more are expected from 2027, and IT providers have committed more than US$1.7 billion to Offers and Orders. Set against an association of more than 370 member airlines, seven is fewer than one in fifty. IATA also said reconciliation, settlement and revenue accounting should be built into the move to Orders from the start, an acknowledgement that the finance plumbing is not settled.
A caveat about Macao itself. The programme gave agentic AI two dedicated sessions, one on search disruption and one framing AI and Offers and Orders as mutually reinforcing. Lufthansa Group, Air France-KLM, Air India and Kenya Airways were among the announced airline speakers. TDN has found no published account of what any of them said on those panels, so this article treats Macao as a statement of industry intent and tests it against what has actually shipped.
What agents do today
“Agentic” is used to cover three different levels of capability, a TDN framing rather than an industry standard. Discovery means asking for options. Live shopping means comparing real, priced offers. An authorised transaction means the agent buys, changes or refunds on the traveller’s behalf. Among the documented deployments TDN reviewed, airline-run applications sit almost entirely in the first two, while autonomous transactions are emerging mainly through intermediaries.
Virgin Atlantic became the first airline to put an app inside ChatGPT in April, and Iberia, Virgin Australia, Condor, Southwest and easyJet have followed. Southwest’s October launch is the clearest example. According to reporting summarised by Modern Airline Retailing, ChatGPT lets travellers compare schedules, availability and fares, then sends them to Southwest’s own website to book, where seats, ancillaries, loyalty and payment stay with the airline. Expedia and Booking.com have run similar hand-off apps inside ChatGPT since October 2025. One industry review reports that OpenAI withdrew its own in-chat checkout from the main ChatGPT interface in March, which TDN has seen from that source only.
Google is further along on hotels than flights. Hotel booking in AI Mode began rolling out in the United States in late August, while for flights it tracks prices across more than 300 airlines and sites and, according to one guide, sends the buyer to the airline’s website to purchase. Flight booking was announced in November 2025 and had not launched at the time of the most recent reporting TDN could find.
Where an agent does complete a flight purchase, an intermediary is in the chain. Mindtrip launched flight booking in May on Sabre’s Mosaic platform with PayPal handling checkout, which Sabre’s chief executive referred to on the first-quarter call. On the second-quarter call Sabre said its active pilot and production partners for agentic APIs and its MCP server had doubled from 30 to 60, and that agents could handle ticket reissues, exchanges and itinerary changes. A 21 September release went further, claiming nearly 80 customers piloting or in production, among them Virgin Australia, Flight Centre and Internova, and saying they were already generating real bookings. These are company figures that combine pilots with production and give no volumes. Travelport announced an MCP-based interface over its Trip Services platform in May with Cognizant and Anthropic, with first customer-facing capabilities expected before the end of 2026. Amadeus, with Microsoft, published a June report on five airline use cases and said it had successfully tested an agentic approach to voice rebooking and planned to move it into production. Whether any of the three is processing material volumes of autonomous airline orders is not disclosed.
The most useful independent evidence is Bain’s March test. Three large language models were given 60 non-branded prompts about routes flown by three large European full-service carriers. Airline websites were accessed directly only about 5 per cent of the time, with the models preferring online travel agencies. That is one test, not a measure of all AI flight searches. In the booking test, no tool reliably reached an airline’s payment page, browser agents stalled on date pickers for ten to 20 minutes, and OTAs outperformed airline sites.
Who gains and who pays
Four things decide who holds power in an agent-mediated sale: who is seen, which offer is chosen, who holds the data and who takes the payment. Today’s live airline deployments are designed to keep the last two with the airline. The first two are where the exposure sits.
Bain found that models gravitate towards the source with the easiest downstream interaction, and that airlines appeared in the top three results on their home-market routes but less often on transit flows. TDN has found no platform that publishes the criteria it uses to rank airline results inside an agent. An airline can hold the transaction through a hand-off and still have no say in how it is presented next to a competitor or an OTA.
The cost side is less discussed. IATA’s October 2025 Look-to-Book white paper introduced metrics such as Offer-to-Order and compute-to-order precisely because shopping volume carries a cost that conversion does not recover, and it addressed the role of generative and agentic AI in raising that volume. OAG’s chief executive put the problem plainly to PhocusWire: every time somebody looks, it costs cash. Compare that with the incumbent models. Sabre’s chief executive said on the first-quarter call that using its Marketplace services costs an airline or hotelier roughly 1.5 per cent of the value of the ticket or booking on average. That is a transaction-linked benchmark, not an equivalent of search costs. An agent that runs hundreds of fare searches before a hand-off to the airline’s site produces a different arrangement. The platform that owns the conversation earns attention, while the airline bears the cost of making its inventory searchable. TDN has found no published commercial terms between an airline and an AI platform for agent-originated traffic, whether commission, referral fee or search charge.
That gap is where the GDSs and aggregators see their opening. Sabre, Travelport and Amadeus are each positioning their systems as the way an agent reaches airline content in a form it can use. TPConnects added an MCP orchestration layer to its Astra NDC platform in March and to its Iris aggregator in April, aimed at normalising NDC schema versions from 18.2 to 24.4. The strategic argument, put by one executive to PhocusWire, is that an airline publishing an MCP server lets an agent reach inventory without conforming to that airline’s specific NDC implementation. It lowers the cost of being reachable, and it hands whoever operates the MCP server a gatekeeping position. An intermediary that stays the agent’s preferred tool keeps a toll; one that only translates formats risks redundancy.
For agencies and travel management companies, TDN found little verifiable evidence either way. A Phocuswright survey found that more than 60 per cent of travel businesses were experimenting with or scaling agentic AI, though only 6 per cent were actively scaling. How an agent-originated booking would be compensated, if at all, is not documented anywhere TDN could find.
Offers, Orders, servicing and payment
An Offer is a priced, time-limited product. A language model can describe one convincingly, but it cannot confirm that sellable inventory exists, that the fare will be honoured or that the bag allowance is right. That confirmation has to come from the airline’s retailing system, and the commit and the servicing record have to live in an Order. This is the sound logic behind IATA’s formulation, and it is also its weakness. Outside the seven airlines IATA counts, agent-sold tickets presumably still depend on existing ticketing and booking records. Sabre says its MCP server lets agents handle reissues and exchanges, but a servicing action through a translation layer is not the same as a native Order, and the Macao figures suggest most airlines are not there yet. That is TDN’s inference from IATA’s numbers and has not been tested against an operating airline.
Payment is where the technology is furthest developed and the liability least settled. Visa and Mastercard have both built agent-specific tokens, with Visa Intelligent Commerce issuing credentials that let an agent pay without exposing the card number. In principle a scoped token suits an airline well, because it can be limited by merchant, amount and time. Existing card-network dispute rules still apply to these purchases. What no source TDN reviewed settles is how they treat agent-specific cases, such as who bears the loss when an agent buys the wrong fare, a traveller disputes a purchase they delegated, or a compromised agent is used to commit fraud. A payments working group launched by EPAA and HSBC on agent payment liability in Asia Pacific suggests the question is open. TDN found no airline-specific chargeback framework for agent-initiated purchases.
Payment orchestration could therefore become a competitive advantage in a quieter way than the marketing implies. An airline that accepts network tokens, local methods and multiple currencies will convert more of the agent traffic it has paid to serve. One that cannot loses the sale at the final step, after bearing the cost of every step before it.
Africa and emerging markets
Africa is not one distribution market, and the evidence shows it. Kenya Airways was the first Sub-Saharan carrier to distribute NDC content through the Amadeus Travel Platform in April 2025, then selected Sabre on 22 September to replace its core reservations and ticketing platform, with Branchspace building a retailing layer. Neither announcement says the Amadeus NDC distribution will end. Air Tanzania chose SabreSonic and Sabre Mosaic NDC IT in August. Ethiopian Airlines holds Level 3 NDC certification from IATA, and EgyptAir became the first Middle East and Africa airline to deploy NDC 24.4 in July. In September, Wakanow became the first African travel company to offer Lufthansa Group NDC content through a direct API.
Those are real steps toward Offers and Orders. None is an agentic deployment, and TDN found no publicly documented African airline or agency running an agent-facing booking product in production. What the pattern does show is how agent access is likely to arrive. The carriers moving fastest are doing so on vendor platforms, and the vendors selling those platforms are the same ones selling agentic APIs. For an airline that could never have funded its own API programme, inheriting an MCP endpoint from its core system supplier is cheap and fast. It is also a dependency: the supplier sets the interface, the terms and the data flows, and the airline learns how its inventory is being queried through the supplier’s reporting. That is analysis, not documented fact.
Smaller carriers face a harder version of the cost problem. A national carrier with a modest technology budget has less room to absorb search volume it does not monetise, and Bain’s advice that airlines which join AI platforms late risk accepting unfavourable economics lands hardest on those with the least negotiating weight.
Readiness may also be less of a choice than the vendor narrative implies, if one unverified claim holds. An open-source project called LetsFG lists Kenya Airways, Ethiopian Airlines, Air Peace, Royal Air Maroc and other African carriers among the airlines its agent tools can search and book, and describes a service that buys the ticket on the traveller’s card and returns the airline’s booking reference. Its repository offers no evidence that any airline is party to it, and TDN has not verified how it reaches their inventory. If the claim holds, agents can already reach carriers that have built nothing for them, and the airline’s only decision is whether to shape that access or leave it to third parties.
Payments add the least discussed constraint. IATA reported in December 2025 that US$1.2 billion of airline funds was blocked from repatriation at the end of October 2025, with 93 per cent of it in Africa and the Middle East. An agent changes who is buying. It does not change whether a carrier selling in a local currency can convert the proceeds. Agents will pay with whatever rails a merchant accepts, so the airlines best placed to benefit are those that can accept diverse local methods and settle in hard currency. Whether agent-originated sales would ease or worsen exposure to blocked funds has not been studied in any source TDN found.
The question nobody has priced
Airlines are pursuing a sensible defence. They are letting AI platforms into the conversation while keeping the sale, the payment and the servicing on their own systems, and they are building Offers and Orders as the foundation that makes those transactions dependable. Macao confirmed that this is IATA’s strategy. It did not show that the foundation is ready, or that anyone has agreed what an agent-originated shop and sale should cost.
Every previous channel came with a price. The GDS charges per booking, the OTA takes a commission, metasearch sells clicks. AI agents so far arrive without a published price, and airlines are paying for the search while the platforms collect the attention. The first airline, GDS or AI platform to publish terms for agent-originated traffic will set the benchmark the others have to answer, and will show whether this is a new channel or a different distribution model. Until then, the honest description of the industry’s position is that it has agreed on the architecture and left the economics unwritten.