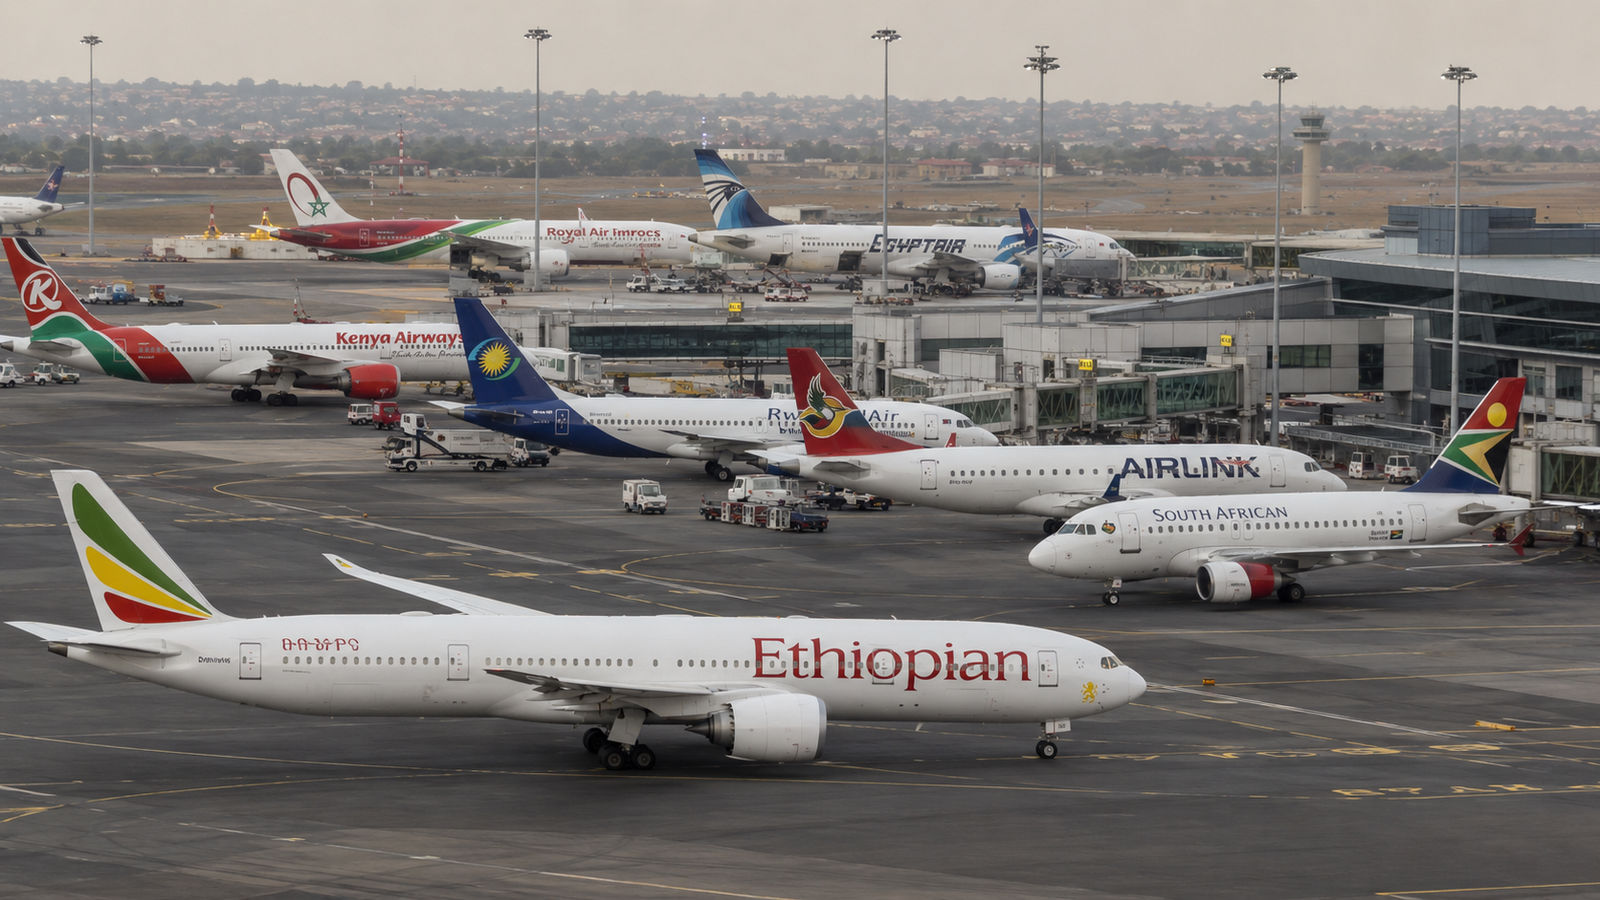
IATA published its August traffic data on 30 September, and the headline figure was a 0.8% fall in global passenger demand. That number hides a split that matters more than the average. Strip out Middle East carriers and demand grew 0.6%. In IATA’s regional load factor table, the two lowest figures belong to Africa (77.5%) and the Middle East (78.9%), the two markets TDN covers most closely.
The numbers
Middle East carriers recorded demand 14.6% lower than August 2025 while capacity fell 9.3%, leaving the load factor at 78.9%, down 4.9 points. On international routes alone, demand fell 14.2% against a 9.0% capacity cut. IATA says the decline worsened in August, reversing a gradual stabilization that had followed the Iran war in February. Traffic between the Middle East and Asia contracted 11.7%, compared with 8.6% in July.
Africa moves in the opposite direction on demand and arrives at a similar place on load factor. African airlines grew total demand 4.4% on 7.2% more capacity, producing a load factor of 77.5%, down 2.1 points. On international routes, demand rose 6.7% against 8.3% more capacity. For comparison, the global load factor was 85.1%, Europe reached 87.5% and Asia-Pacific 85.9%.
The trend matters as much as the month. IATA’s July release showed African airlines growing international demand 6.4% and Middle East carriers down 9.5%. Africa has grown steadily. The Middle East improved in July and then slid back.
Two different problems
The two regions share a weak load factor but not a cause. In the Middle East, passengers are leaving faster than airlines can remove seats. Capacity fell 9.3% and demand fell 14.6%, so each cut is being overtaken by lost traffic. IATA’s chief economist, Marie Owens Thomsen, pointed to reduced traveler purchasing power from higher energy prices and to geopolitical instability as factors to watch. That points to a demand problem that emerged around the February conflict and worsened again in August.
Africa has a fundamentally different problem. Demand is growing, but seats are arriving faster than passengers. That is still a serious issue for carriers working with thin margins, because capacity growing ahead of demand can pressure yields as well as load factors. Engineering News reported in December 2025 that IATA’s regional vice president for Africa and the Middle East put African airline margins at 1.3%. A region adding capacity ahead of demand on margins that thin has little room to absorb a weak quarter.
Where distribution and payments come in
IATA’s data measures traffic. It says nothing directly about how seats are sold or how airlines are paid, so what follows is analysis, not something the data proves.
When load factors fall, airlines need to fill seats through every available channel, and they need to collect revenue quickly. Both are harder in emerging markets. IATA reported that African countries held USD774 million in blocked airline funds as of 31 March 2026, with Algeria alone at USD258 million, according to CAPA’s report of the release. Revenue that is earned but cannot be repatriated is revenue that cannot cover the cost of added capacity.
On the sales side, a panel at the African Airlines Association’s SkyConnect Dialogues in 2025 described airline distribution in Africa as highly fragmented, with over 70% of ticket sales in some markets still coming through travel agencies. An airline growing seats by more than 8% in that environment is likely to depend heavily on intermediaries to fill them, and on settlement systems to return the cash. In the Gulf, carriers facing a 14% demand drop are likely to be reassessing which channels deliver passengers at acceptable cost, though that is a question for the airlines, not a finding.
What we cannot say
IATA notes that all figures are provisional, include estimates for missing data, and are subject to revision. Africa accounts for only 2.2% of world traffic, so these are regional signals, not global ones. We have not yet spoken to airlines, agencies or payment providers about how these traffic shifts are affecting their sales channels or settlement, and until we do, the link between load factors and distribution stress remains a hypothesis.
What to watch
Three things will test this. IATA’s September traffic data, if it follows the usual pattern, will land at the end of October and show whether the Middle East slide continues. IATA says forward schedules show 2.0% more seats globally in October, so airlines are still planning for growth. IATA’s next blocked funds update will show whether the USD774 million African figure is moving. And on 28 and 29 October, IATA holds its World Financial and Passenger Symposiums in Macao, where payment modernization and airline retailing are on the agenda, and where emerging-market airlines can say whether the global conversation reflects their reality.
The point
Growth is not health. For airlines in emerging markets, the next twelve months will not be decided by whether passengers want to fly, since African international demand grew in both July and August. It will be decided by whether the sales channels and payment rails that sit between the seat and the cash can keep up with the capacity being added, and whether Gulf carriers can rebuild demand before cutting capacity further. The weakest load factors in global aviation are occurring in regions where distribution can be fragmented and where moving airline revenue can still be difficult. IATA’s data cannot tell us whether those factors are contributing to the pressure. That is the distribution question sitting underneath the traffic numbers, and it deserves closer scrutiny.